

Maharashtra’s Micro-Business Outstanding Balances Grew at 18% CAGR for Individual Entrepreneurs and 13% For Enterprises Over Three Years
· Maharashtra leads India’s micro-business credit market at ₹4.07 lakh crore as individual borrowing outpaces enterprise lending
· Around 43.8 lakh individual entrepreneurs in Maharashtra have never borrowed as enterprises, with 69% having credit scores above 730
· Nationally, micro business entrepreneurs account for ₹29.6 lakh crore in outstanding commercial credit, with individual borrowing growing at 21% CAGR
Pune, India, 4th November 2026: Maharashtra remains India's largest micro business entrepreneur (MBE) credit market, with outstanding balances reaching approximately ₹4.07 lakh crore as of June 2026. Business-purpose borrowing by individuals continues to grow faster than lending to micro businesses, with outstanding balances held by individual entrepreneurs expanding at an 18% compounded annual growth rate (CAGR) over the last three years, compared with 13% among micro businesses. This reflects the growing role of individual borrowing in financing entrepreneurial activity across the state.
This expansion is also bringing attention to a sizeable opportunity in enterprise-level credit. Approximately 43.8 lakh individual entrepreneurs in Maharashtra had never borrowed as enterprises as of March 2026, even as 69% of them had CIBIL Scores of above 730. These findings, from Micro Business Entrepreneurs in India: Growth, Transformation & Emerging Opportunities, a joint study by TransUnion CIBIL and the National Small Industries Corporation Limited (NSIC), highlight the potential to widen access to structured business financing among eligible entrepreneurs who already have established individual credit profiles, subject to applicable lender policies, underwriting criteria and regulatory requirements.
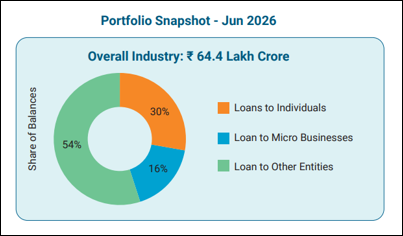
Across India, MBEs accounted for ₹29.6 lakh crore in outstanding commercial credit as of June 2026, representing nearly half of the overall commercial credit portfolio. Of this, ₹19.1 lakh crore was held by individuals borrowing for business purposes and ₹10.5 lakh crore by micro businesses. Individual borrower balances grew at a 21% CAGR over three years, compared with 12% among micro businesses, indicating that business-purpose borrowing in individual capacity is expanding faster than enterprise-level credit.
Chart 1 – Commercial Outstanding Balances
Maharashtra's Entrepreneurial Credit Growth Reflects Expanding Trade and Services Activity
Maharashtra's micro business credit landscape reflects the state's diverse entrepreneurial ecosystem, with trade, services and transportation-linked industries supporting business activity. Trade accounts for 29% of outstanding balances among micro businesses, while construction and transport-linked sectors have expanded at an approximately 18–19% CAGR over the last three years. LAPs remain the largest financing product, accounting for 40% of overall MBE balances, while commercial vehicle financing continues to support entrepreneurial activity. Private lenders and NBFCs together account for nearly 68% of individual business borrower balances, reflecting their role in financing entrepreneurs across the state.
Mr. Bhavesh Jain, MD & CEO, TransUnion CIBIL, said: “Maharashtra's entrepreneurial ecosystem spans a wide range of economic activities, from trade and professional services to construction and transportation. As businesses grow, their financing requirements become more complex, extending from day-to-day working capital to equipment purchases, capacity expansion and longer-term investments. This creates an opportunity for lenders to develop a more comprehensive understanding of entrepreneurs' credit journeys and provide solutions aligned with their evolving business needs. Building stronger enterprise-level credit relationships may help eligible businesses access financing appropriate to different stages of growth, subject to lender policies and applicable regulations, while supporting responsible lending and long-term portfolio quality.”
Bridging the Gap Between Individual Borrowing and Enterprise-Level Credit
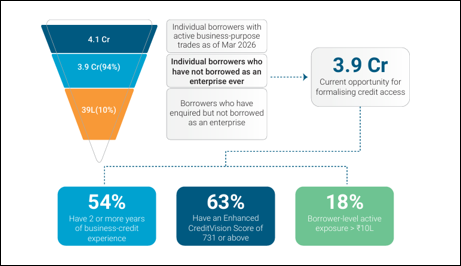
A significant number of India's MBEs have established borrowing histories in their individual capacity but have yet to access credit as formal business entities. As of March 2026, approximately 3.9 crore individual business borrowers across India had never borrowed in an enterprise capacity. Among them, 54% had two or more years of business-credit experience, while 63% had a CIBIL Score of above 730, indicating a substantial pool of borrowers with established credit profiles.
For lenders, this represents an opportunity, subject to their applicable credit policies, underwriting criteria and regulatory requirement, to support entrepreneurs as they progress from individual business borrowing towards enterprise-level credit. Greater access to working-capital facilities, cash credit and overdraft products could help businesses meet evolving financing requirements, while reducing their dependence on personal assets as collateral.
Chart 2 – Opportunity for Formalising Enterprise Credit Access
Maharashtra's opportunity for deeper enterprise credit access is supported by one of the country's largest pools of individual business borrowers. Approximately 43.8 lakh entrepreneurs had never borrowed as enterprises as of March 2026, with 69% having CIBIL Scores of above 730. As of June 2026, 55% of outstanding individual business borrower balances belonged to the above prime segment1. Portfolio performance has also strengthened significantly, with 90+ days delinquency declining by approximately 164 basis points over three years to 2.0%, one of the sharpest improvements among major states. The combination of an established borrower base and improving repayment performance provides a foundation for expanding access to enterprise-level financing among eligible entrepreneurs.
Secured Lending Remains Central to Micro Business Credit
Across India, lending to micro business entrepreneurs remains predominantly supported by secured and collateral-backed products. LAPs accounted for ₹10.9 lakh crore in outstanding balances as of June 2026, making it the largest product category, followed by cash credit and overdraft facilities at ₹5.6 lakh crore and commercial vehicle loans at ₹5.0 lakh crore. These financing patterns reflect the continued importance of collateral in supporting business borrowing, while also highlighting opportunities to expand cash-flow-based and working-capital-oriented lending.
The expansion in micro business credit has been accompanied by improving portfolio quality. Overall delinquency levels declined from approximately 3.0% in June 2023 to 1.9% in June 2026, reflecting stronger repayment performance amid sustained credit growth. As financing becomes more accessible, understanding the credit needs and repayment capacity of different entrepreneur segments will remain important for maintaining portfolio resilience.
Enabling the Next Phase of Micro Business Growth
As India's entrepreneurial ecosystem expands, the next phase of micro business credit growth will increasingly depend on enabling businesses to progress towards more structured enterprise financing. Wider adoption of cash-flow-based underwriting, credit guarantee mechanisms and digital financial information can help lenders assess viable businesses beyond traditional collateral-based approaches.
Strengthening the connection between individual business borrowing and enterprise-level credit can support greater formalisation, improve access to financing suited to different stages of business growth and create new opportunities for entrepreneurs across India.
****
1. Enhanced CreditVision (CV) score ranges are: below prime = 300-730; prime = 731-800; above prime = 801-900.
Disclaimer: This press release is based on findings from the study Micro Business Entrepreneurs in India: Growth, Transformation & Emerging Opportunities jointly prepared by TransUnion CIBIL and National Small Industries Corporation Limited (NSIC). The information and insights presented are based on analysis of available data and are intended solely for informational purposes. Nothing in this press release constitutes financial, credit, investment, legal or other professional advice, nor should it be construed as a recommendation, solicitation, approval or assurance regarding the availability, extension or suitability of any credit facility or financing product. Any lending decision remains subject to the applicable policies, underwriting criteria, risk assessment processes and regulatory requirements of the concerned lender.
About TransUnion CIBIL
India’s pioneer credit information company, TransUnion CIBIL, ensures the credit history of each person and business entity is reliably represented.
We have developed technology and innovative solutions across core credit, risk and advanced analytics. As a result, consumers and businesses can transact with confidence and achieve great things. We call this Information for Good® — and it leads to economic opportunity, great experiences, and personal empowerment for millions of people and commercial entities in India.
Our customers in India include banks, credit institutions, NBFCs, housing finance companies, microfinance companies, telecom companies and insurance firms.
For more information visit: https://www.transunioncibil.com/